MSME Samadhaan Filing: 45-Day Payment Mandate & 3x Compounded Interest Recovery under MSMED Act 2006
 Authored by: Advocate Kishan Kumar (Advocate & Legal Consultant)
Quick Summary & Strategic Key Takeaways
- The Mandatory 45-Day Payment Rule: Section 15 of the MSMED Act, 2006 establishes that buyers must pay Micro and Small suppliers within 15 days (if no written agreement exists) or within a maximum non-extendable statutory cap of 45 days under written contracts.
- 3x Compounding Monthly Interest: Section 16 mandates that delayed payments attract compound interest with monthly rests at three times (3x) the RBI Bank Rate. This interest is statutory, non-waivable, and strictly non-deductible under Income Tax.
- Section 43B(h) Income Tax Disallowance: Under Section 43B(h) effective AY 2024-25, buyers who fail to clear MSME invoices within 45 days cannot claim the expense as a tax deduction in that financial year, creating massive corporate tax liabilities.
- The 75% Pre-Deposit Barrier: Under Section 19 and Gujarat State Civil Supplies (2023), buyers challenging an MSEFC arbitral award in court must mandatorily deposit 75% of the awarded amount upfront, virtually eliminating frivolous appeals.
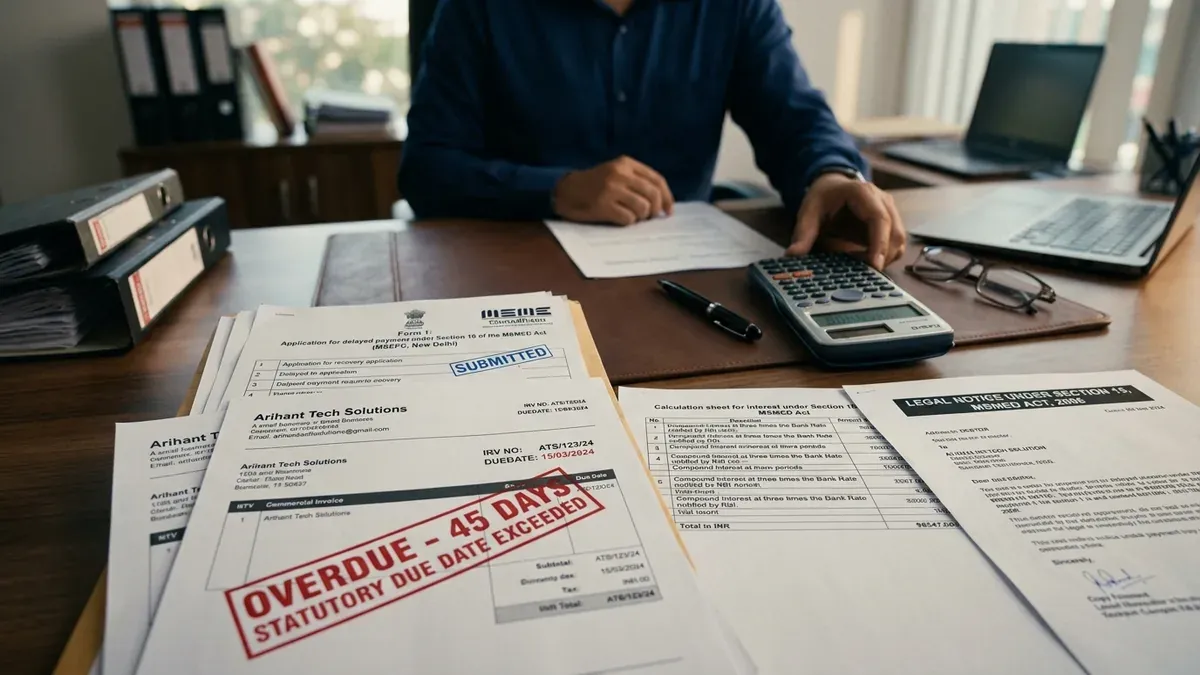
1. Statutory Framework: Micro, Small and Medium Enterprises Development Act 2006
Delayed payments from large corporate buyers, public sector undertakings (PSUs), and mid-sized enterprises have historically been the primary cause of working capital starvation and insolvency among Indian small businesses. To eradicate this systemic asymmetry, Parliament enacted the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006, embedding an aggressive statutory recovery framework under Chapter V (Sections 15 to 25).
The core legislative intent of Chapter V is to override ordinary commercial contracts and fast-track cash flow realization. Under Section 24 of the Act, the provisions of Sections 15 to 23 have an express non-obstante clause, meaning they override any inconsistent term contained in any agreement, purchase order, or general statute (including the Indian Contract Act, 1872 and the Code of Civil Procedure, 1908).
2. Section 15 Statutory Payment Timelines: 15-Day vs. 45-Day Rule
Under Section 15 of the MSMED Act, 2006, the buyer is statutorily obligated to pay the supplier for goods supplied or services rendered within strict parameters:
- The 15-Day Default Rule (No Written Agreement): Where there is no written commercial agreement between the buyer and the supplier specifying credit terms, payment must be remitted on or before the 'appointed day' — which is strictly defined as the day immediately following the expiry of fifteen (15) days from the day of acceptance of the goods or services.
- The 45-Day Ceiling Rule (Written Agreement): Where a written contract or purchase order exists between the parties, the agreed credit period cannot under any circumstances exceed forty-five (45) days from the day of acceptance or deemed acceptance. Any commercial clause purporting to extend credit to 60, 90, or 120 days is void to the extent of the excess over 45 days.
3. Section 16 Penal Compound Interest: 3 Times RBI Bank Rate
Where a buyer fails to remit payment within the Section 15 timeline, Section 16 triggers an immediate, non-discretionary statutory financial penalty:
"Where any buyer fails to make payment of the amount to the supplier, as required under section 15, the buyer shall, notwithstanding anything contained in any agreement between the buyer and the supplier or in any law for the time being in force, be liable to pay compound interest with monthly rests to the supplier on that amount from the appointed day or, as the case may be, from the date immediately following the date agreed upon, at three times of the bank rate notified by the Reserve Bank."
Key operational characteristics of Section 16 interest include:
- Monthly Compounding: Interest compounds on a monthly basis, creating an exponentially escalating financial burden that quickly dwarfs ordinary civil court interest (which is typically 6% to 9% simple interest under Section 34 CPC).
- Three Times RBI Bank Rate: With the RBI Bank Rate hovering around 6.50% to 6.75%, the effective Section 16 interest rate exceeds 19.5% to 20.25% compounded monthly.
- Tax Inadmissibility (Section 23): Under Section 23 of the Act, penal interest paid or payable by a buyer under Section 16 is expressly disallowed as a tax-deductible expenditure under the Income Tax Act, 1961.
4. Section 43B(h) Income Tax Revolution: Corporate Expense Disallowance
The implementation of Section 43B(h) of the Income Tax Act, 1961 (enacted via Finance Act, 2023, applicable from Financial Year 2023-24 / Assessment Year 2024-25) has completely altered corporate compliance dynamics across India.
Under Section 43B(h), any sum payable by a buyer to a registered Micro or Small enterprise beyond the statutory timeline specified in Section 15 of the MSMED Act (15 days or maximum 45 days) shall be allowed as a tax deduction strictly on actual payment basis. The practical consequences for corporate buyers are severe:
- Year-End Disallowance: If a buyer purchases goods worth Rs. 1 Crore from an MSME in January and fails to settle the invoice within 45 days, and the invoice remains unpaid on 31st March, the entire Rs. 1 Crore purchase expense is disallowed and added back to the buyer's taxable corporate income.
- Massive Tax Inflow: Corporate buyers face an immediate tax liability of approx. 25% to 30% on the disallowed amount, forcing corporate CFOs and procurement heads to prioritize MSME vendor clearances over all other creditors.
5. MSEFC Dispute Resolution under Section 18: Conciliation to Arbitration
When amicable recovery attempts fail, an MSME files an online application on the MSME Samadhaan portal, triggering statutory dispute resolution before the state Micro and Small Enterprises Facilitation Council (MSEFC) under Section 18:
- Stage 1 — Mandatory Conciliation (Section 18(2)): The Council initiates statutory conciliation proceedings under Sections 65 to 81 of the Arbitration and Conciliation Act, 1996. The Council acts as a conciliator to broker an agreed settlement between the buyer and supplier.
- Stage 2 — Reference to Arbitration (Section 18(3)): If conciliation fails or terminates without settlement, the Council either takes up the dispute for arbitration itself or refers it to any institution or centre providing alternate dispute resolution services. The arbitration is conducted under the Arbitration and Conciliation Act, 1996, and culminates in a binding statutory Arbitral Award.
- Statutory 90-Day Target: Under Section 18(5), every reference made to the Council must be decided within a target timeframe of ninety (90) days from the date of making such reference.
6. The 75% Pre-Deposit Barrier under Section 19: Mahakali Foods Doctrine
Once an MSEFC arbitral award is passed in favor of the MSME, defaulting buyers face an almost insurmountable procedural barrier to delay execution. Under Section 19 of the Act, no court shall entertain any application for setting aside any decree, award, or order made by the Council unless the appellant/buyer deposits with the court seventy-five percent (75%) of the awarded amount.
In the authoritative 3-Judge Bench judgment of Gujarat State Civil Supplies Corporation Ltd. v. Mahakali Foods Pvt. Ltd. (2023) 6 SCC 401, the Supreme Court ruled that:
- The provisions of Chapter V of the MSMED Act have overriding effect over the Arbitration and Conciliation Act, 1996.
- The 75% pre-deposit under Section 19 is an absolute, mandatory condition precedent; no court has the discretion to waive or reduce this deposit.
- The court has the discretion to disburse a reasonable percentage of the deposited amount to the MSME supplier pending final adjudication.
7. The Udyam Registration Timing Rule: Silpi Industries Precedent
In Silpi Industries v. Kerala State Road Transport Corporation (2021) SCC OnLine SC 439, the Supreme Court laid down an indispensable jurisdictional rule: Udyam Registration must pre-date the supply contract.
The Court held that an enterprise cannot claim the benefits of Chapter V (Sections 15 to 25) if it was not registered under the MSMED Act on the date when the commercial agreement was executed and the goods or services were delivered. Obtaining a Udyam Certificate retrospectively after delivering goods does not confer retrospective jurisdiction on the MSEFC. Enterprises must maintain active Udyam registration prior to executing any purchase orders.
8. Step-by-Step MSME Samadhaan Filing & Enforcement Roadmap
To recover delayed dues through the official statutory mechanism, follow this procedural roadmap:
- Step 1 — Issue Formal Section 15 Demand Letter: Issue a formal demand letter to the buyer referencing Udyam Registration, invoices, delivery proofs, and citing Section 15, Section 16 (3x interest), and Section 43B(h) of the Income Tax Act, giving 7 days to settle.
- Step 2 — Online Application on MSME Samadhaan: Visit the official Ministry of MSME portal (samadhaan.msme.gov.in), authenticate via Udyam credentials, and upload invoice copies, delivery challans, and contractual purchase orders.
- Step 3 — Automated Intimation & Mutual Settlement: The portal automatically dispatches an official intimation to the buyer, allowing 15 days for online response. Over 40% of cases settle at this stage to avoid statutory scrutiny.
- Step 4 — Facilitation Council Hearings: If unpaid, the application is converted into a formal case before the state MSEFC. Attend conciliation hearings; if the buyer fails to appear, the Council terminates conciliation and commences statutory arbitration.
- Step 5 — Award Execution under Section 36: The final arbitral award passed by the MSEFC has the status of a civil court decree. Execute the award under Order XXI of the Code of Civil Procedure, 1908 before the District Court, attaching the buyer's commercial bank accounts.
9. Actionable Debt Recovery Checklist for Micro & Small Enterprises
MSME Statutory Debt Recovery Blueprint
- Print Udyam Number on All Tax Invoices: Prominently display your Udyam Registration Number, NIC code, and Section 15 payment terms on every tax invoice and delivery challan.
- Maintain Concrete Proof of Delivery (POD): Ensure physical delivery challans, lorry receipts (bilty), and electronic gate passes are signed and stamped by buyer warehouse personnel.
- Audit Ageing Debt Beyond 45 Days: Generate weekly debtor ageing reports flagging every invoice crossing the 45-day threshold to issue statutory demand notices.
- Leverage Section 43B(h) in Q4 Communications: In January to March, serve specific reminders citing corporate tax expense disallowance to corporate buyers with pending balances.
- File Promptly on MSME Samadhaan Portal: File online applications before the expiry of the 3-year limitation window under the Silpi Industries doctrine.
- Enforce Arbitral Decrees Aggressively: Retain commercial advocates to execute MSEFC awards through garnishee orders under Order 21 Rule 46 CPC to freeze buyer bank accounts.
Frequently Asked Questions on MSME Samadhaan & 45-Day Payment Rule
Key statutory answers and recovery guidance curated by Commercial Litigation Advocates in Delhi NCR & Haryana.
What is the mandatory statutory payment timeline under Section 15 of the MSMED Act, 2006?
Section 15 of the MSMED Act 2006 mandates that the buyer shall make payment to the MSME supplier on or before the agreed date. However, the statute enacts two non-negotiable boundaries: (1) Where there is no agreed credit period in writing, payment must be made within fifteen (15) days from the day of acceptance of goods or services; and (2) Where there is a written agreement specifying credit terms, such agreed period CANNOT exceed forty-five (45) days. Any contractual clause stipulating 60, 90, or 120 days is statutorily overridden by the 45-day cap.
How is the mandatory compound interest calculated under Section 16 of the MSMED Act?
Under Section 16 of the MSMED Act 2006, if the buyer fails to remit payment within the Section 15 timeline, the buyer is statutorily liable to pay compound interest with monthly rests at three times (3x) the Bank Rate notified by the Reserve Bank of India (RBI). This interest rate is mandatory, statutory, and non-waivable by contract. Furthermore, Section 23 of the Act strictly prohibits the buyer from claiming this penal interest as a deductible business expense under the Income Tax Act, 1961.
What is the impact of Section 43B(h) of the Income Tax Act on buyers delaying MSME payments?
Introduced via the Finance Act 2023 (effective from Assessment Year 2024-25), Section 43B(h) of the Income Tax Act 1961 provides that any sum payable by an assessee to a registered Micro or Small enterprise beyond the time limit specified in Section 15 of the MSMED Act (within 15 days or maximum 45 days) shall be allowed as a tax-deductible expenditure ONLY in the financial year in which such sum is actually paid. If a corporate buyer fails to clear an MSME invoice by 31st March, the unpaid amount is added back to the buyer's taxable corporate profit, attracting immediate income tax at standard rates (approx. 25% to 30% plus surcharges).
Is Udyam Registration mandatory at the time of supply to claim relief under MSME Samadhaan?
Yes. In the landmark judgment of Silpi Industries v. Kerala State Road Transport Corporation (2021) SCC OnLine SC 439, the Supreme Court ruled that to claim the statutory benefits of Chapter V of the MSMED Act (including 45-day payment rules, 3x interest, and MSEFC facilitation), the supplier must be registered under Udyam (or former EM-II) ON OR BEFORE the date of entering into the commercial contract and supplying the goods or services. Registration obtained retrospectively after completing supply does not confer statutory jurisdiction before the MSEFC.
What is the mandatory 75% pre-deposit requirement under Section 19 of the MSMED Act?
Under Section 19 of the MSMED Act 2006, no court or appellate authority can entertain any application to set aside any decree, award, or order made by the MSEFC (or arbitrator) unless the appellant/buyer deposits with the court seventy-five percent (75%) of the awarded amount. In Gujarat State Civil Supplies Corporation Ltd. v. Mahakali Foods Pvt. Ltd. (2023) 6 SCC 401, the Supreme Court confirmed that the 75% pre-deposit is an absolute, non-waivable statutory condition precedent to challenge an MSEFC award under Section 34 of the Arbitration and Conciliation Act, 1996.
Can Medium enterprises and wholesale/retail traders use the MSME Samadhaan portal?
No. The fast-track recovery provisions under Chapter V (Sections 15 to 25) of the MSMED Act apply strictly to 'Micro' and 'Small' enterprises. Medium enterprises are excluded from Chapter V relief. Furthermore, while the Ministry of MSME permitted Wholesale and Retail Traders to register on Udyam via Office Memorandum dated 02.07.2021 for priority sector lending benefits, traders are expressly excluded from initiating debt recovery before the MSEFC under MSME Samadhaan.
What is the statutory limitation period for filing an MSME Samadhaan petition?
Under the Supreme Court ruling in Silpi Industries, proceedings before the MSEFC are subject to the Limitation Act, 1963. The limitation period for filing an application before the Facilitation Council is three (3) years from the date the payment fell due under Section 15. The 3-year limitation clock can be reset by written balance confirmations or part-payments under Sections 18 and 19 of the Limitation Act.